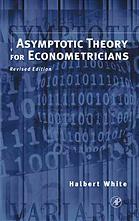
Asymptotic Theory for Econometricians
Halbert White · 1984
Where to buy
Amazon’s price changes daily, so the most accurate place to see it is there, at the moment you buy.
View on AmazonAbout the book
"The amount of financial data created every day by world stock markets, world governments, financial situations, and other sources, is increasing at an enormous rate. Economists and financial analysts need tools to manage these large sets of data in a timely and accurate way. Classical linear models of economics have failed to deal with such large amounts of data, and asymptotic theory is the tool that economists have come to rely on for this type of data management.". "The scope of the book remains the same as that of the First Edition, with sufficient material to fill a full year's course work. This edition also contains updated material on asymptotically efficient instrumental variables estimation, efficient estimation with estimated error covariance matrices, and efficient IV estimation. Exercise solutions have also been updated and expanded.". "Asymptotic Theory for Econometricians is intended both as a reference for practicing econometricians and financial analysts and as a textbook for graduate students taking courses in econometrics beyond the introductory level. It assumes that the reader is familiar with the basic concepts of probability and statistics as well as with calculus and linear algebra, and that the reader also has a good understanding of the classical linear model."--BOOK JACKET.
First sentence: The purpose of this book is to provide the reader with the tools and concepts needed to study the behavior of econometric estimators and test statistics in large samples.
Book details
- Year
- 1984
- Language
- English
- Publisher
- Academic Press
- Editions
- 3
- Pages
- 264
- ISBN
- 9780127466521
Data source: Wikidata