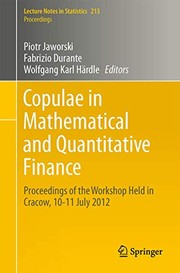
Copulae in Mathematical and Quantitative Finance
Piotr Jaworski, Fabrizio Durante, Wolfgang Karl Härdle · 2013
Where to buy
Amazon’s price changes daily, so the most accurate place to see it is there, at the moment you buy.
View on AmazonAbout the book
Copulas are mathematical objects that fully capture the dependence structure among random variables and hence offer great flexibility in building multivariate stochastic models. Since their introduction in the early 1950s, copulas have gained considerable popularity in several fields of applied mathematics, especially finance and insurance. Today, copulas represent a well-recognized tool for market and credit models, aggregation of risks, and portfolio selection. Historically, the Gaussian copula model has been one of the most common models in credit risk. However, the recent financial crisis has underlined its limitations and drawbacks. In fact, despite their simplicity, Gaussian copula models severely underestimate the risk of the occurrence of joint extreme events. Recent theoretical investigations have put new tools for detecting and estimating dependence and risk (like tail dependence, time-varying models, etc) in the spotlight. All such investigations need to be further developed and promoted, a goal this book pursues. The book includes surveys that provide an up-to-date account of essential aspects of copula models in quantitative finance, as well as the extended versions of talks selected from papers presented at the workshop in Cracow.
Book details
- Year
- 2013
- Language
- English
- Publisher
- Springer London, Limited
- Editions
- 2
- ISBN
- 9783642354076
Data source: Wikidata