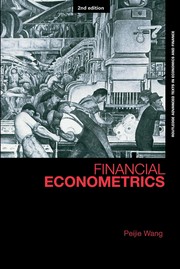
Financial econometrics
Peijie Wang · 2008
Where to buy
Check today’s price on Amazon. We do not show prices because they change daily.
View on AmazonAffiliate link. As an Amazon Associate we earn from qualifying purchases.
About the book
"Refreshingly, every chapter has a section of two or more examples and a section of empirical literature, offering the reader the opportunity to practise right away the kind of research going on in the area. This approach helps the reader develop interest, confidence and momentum in learning contemporary econometric topics." "Graduate and advanced undergraduate students requiring a broad knowledge of techniques applied in the finance literature, as well as students of financial economics engaged in empirical enquiry, should find this textbook to be invaluable."--Jacket. "Financial Econometrics covers all major developments in the area in recent years in an informative as well as succinct way. Subjects covered include: unit roots, co-integration and other comovements in time series, time-varying volatility models of the GARCH type and the stochastic volatility, approach, analysis of shock persistence and impulse responses, Markov switching, present value relations and data characteristics, state space models and the Kalman filter, and frequency domain analysis of time series."
Book details
- Year
- 2008
- Language
- English
- Publisher
- Routledge
- Editions
- 1
- ISBN
- 9780415426701
Data source: Wikidata
More by Peijie Wang