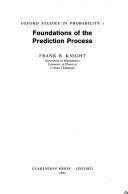
Foundations of the prediction process
Frank B. Knight · 1992
Where to buy
Amazon’s price changes daily, so the most accurate place to see it is there, at the moment you buy.
View on AmazonAbout the book
This book presents a unified treatment of the prediction process approach to continuous time stochastic processes. The underling idea is that there are two kinds of time: stationary physical time and the moving observer's time. By developing this theme, the author develops a theory of stochastic processes whereby two processes are considered which coexist on the same probability space. In this way, the observer' process is strongly Markovian. Consequently, any measurable stochastic process of a real parameter may be regarded as a homogeneous strong Markov process in an appropriate setting. This leads to a unifying principle for the representation of general processes in terms of martingales which facilitates the prediction of their properties. While the ideas are advanced, the methods are reasonable elementary and should be accessible to readers with basic knowledge of measure theory, functional analysis, stochastic integration, and probability on the level of the convergence theorem for positive super-martingales.
Book details
- Year
- 1992
- Language
- English
- Series
- Oxford studies in probability ;
- Publisher
- Clarendon Press
- Editions
- 1
- Pages
- 270
- ISBN
- 9780198535935
Data source: Wikidata